SBLC Leasing
SBLC for Lease: Understanding Leased SBLC Solutions and Providers
An SBLC for lease is a financial arrangement in which an eligible Standby Letter of Credit may be made available to a client for a defined period and under agreed contractual terms. Businesses may explore a leased SBLC when they require a financial instrument to support a legitimate commercial transaction, contractual obligation, trade requirement, or potential financing structure.
The structure of an SBLC lease can vary depending on the parties involved, the issuing institution, the beneficiary, the transaction purpose, and applicable banking and compliance requirements. Because an SBLC is generally issued by a bank or eligible financial institution, businesses should understand the distinction between the institution that issues the instrument and companies that may assist with arranging or coordinating the transaction.
What Is an SBLC for Lease?
An SBLC for lease generally refers to an arrangement where an eligible Standby Letter of Credit is provided for use during an agreed period rather than being permanently owned by the receiving party.
The exact rights and responsibilities depend on the underlying agreement. A leased SBLC may be considered for transactions where a beneficiary requires financial assurance or where an eligible instrument may form part of a broader commercial or financing structure.
Businesses should carefully review the terms before proceeding. Important considerations can include the SBLC amount, validity period, issuing institution, beneficiary, applicable rules, fees, collateral requirements, and permitted use of the instrument.
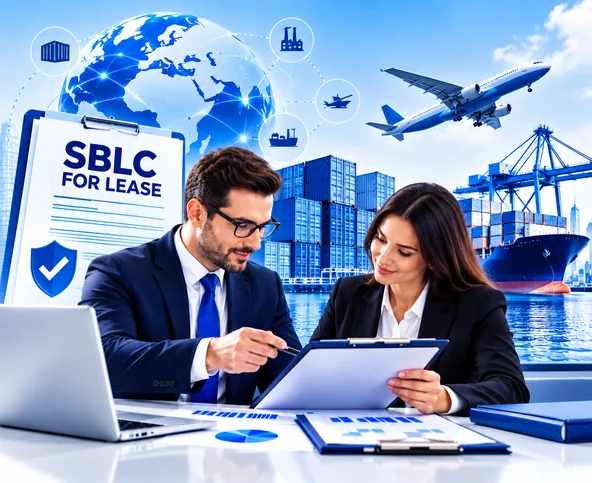
Although each transaction is different, the process may generally involve several stages.
1. Initial Consultation
The applicant explains the purpose of the transaction, required SBLC amount, preferred validity period, beneficiary information, and intended use.
2. Documentation
The parties may request corporate documents, identification, financial information, transaction agreements, beneficiary details, and other supporting documents.
3. Due Diligence
The relevant parties may conduct KYC, AML, sanctions, corporate, financial, and transaction-related checks. Additional information may be required depending on the transaction and jurisdiction.
4. Transaction Structuring
The proposed SBLC lease structure is reviewed, including the issuing institution, beneficiary requirements, fees, collateral, validity period, and responsibilities of each party.
5. Issuing Institution Review
The relevant bank or financial institution determines whether the transaction meets its internal requirements and approval criteria.
6. Issuance and Delivery
If approved, the SBLC is issued according to the applicable terms and delivered through the appropriate banking channels.
The timeline and requirements can vary considerably. An SBLC should not be considered issued until the relevant financial institution has formally completed its procedures and issued the instrument.
Why Do Businesses Consider a Leased SBLC?
Businesses may explore a leased SBLC for several legitimate commercial purposes. Depending on the transaction, potential applications can include:
- International trade transactions
- Contractual financial security
- Project and commercial transactions
- Business expansion
- Financing structures
- Performance-related obligations
- Other approved commercial requirements
An SBLC does not automatically provide cash or guarantee financing. Its usefulness depends on the terms of the instrument and whether the beneficiary or relevant financial institution accepts the proposed structure.
Finding SBLC Lease Providers
Businesses researching lease SBLC providers should conduct appropriate due diligence before entering into an agreement. A provider may act as an arranger, intermediary, consultant, or transaction coordinator, while the actual SBLC may be issued by a separate bank or financial institution.
When evaluating providers, consider whether they clearly explain:
- Who the issuing institution is
- Who the applicant and beneficiary are
- How the SBLC will be issued and delivered
- What documentation is required
- What fees and expenses apply
- What the validity period will be
- Whether collateral or security is required
- How the instrument can be independently verified
- What happens when the lease period ends
Businesses should be particularly cautious about claims of guaranteed issuance, guaranteed financing, immediate approval, or guaranteed monetization.
SBLC Lease and Monetization
Some businesses searching for SBLC lease arrangements may also be interested in monetization. In certain circumstances, an eligible SBLC may potentially form part of a financing or monetization structure.
However, leasing an SBLC does not automatically mean that the instrument can be monetized. The receiving institution or financing party may have its own requirements regarding the issuing bank, instrument wording, transaction structure, beneficiary, collateral, compliance, and documentation.
Any proposed monetization arrangement should therefore be reviewed independently before the business incurs substantial costs or enters into contractual commitments.
Important Considerations Before Leasing an SBLC
Before proceeding with an SBLC lease, businesses should understand the complete transaction structure and all associated obligations.
Review the agreement carefully and confirm the identity of every party involved. The proposed issuing institution and banking communications should be independently verified through appropriate channels.
Businesses should also consider the total cost of the transaction, including arrangement fees, bank charges, due-diligence expenses, collateral requirements, and any other applicable costs.
For significant transactions, independent legal, financial, and banking advice may be appropriate.

FAQ’s
Frequently Asked Questions
Browse our most common questions about fees, identification, mobile services, and legal
requirements.
An SBLC for lease generally refers to an arrangement in which an eligible Standby Letter of Credit is made available to a client for a specified period under agreed terms and conditions.
A leased SBLC may be considered for legitimate commercial purposes such as international trade, contractual security, project transactions, business financing structures, and other approved business requirements.
An SBLC may be arranged through a provider or intermediary, but the actual instrument is generally issued by a bank or eligible financial institution. The roles of the provider and issuing institution should be clearly established.
There is no universal lease period. The validity period depends on the transaction structure, issuing institution, beneficiary requirements, contractual terms, and applicable banking procedures.
A leased SBLC may potentially be considered within certain financing or monetization structures, but monetization is not automatic or guaranteed. The receiving institution must determine whether the instrument meets its requirements.
Businesses should verify the provider’s corporate information, the proposed issuing institution, transaction documents, banking communications, fees, and contractual terms. Independent professional due diligence is recommended before proceeding.