Private Business Lenders
Private Business Lenders: Business Financing Solutions for Commercial Needs
Private business lenders provide financing to companies through lending structures that may operate outside traditional bank lending channels. Businesses may consider private lenders when they need funding for expansion, working capital, equipment, commercial projects, acquisitions, or other legitimate business purposes.
Private business lending can provide businesses with access to different financing structures and repayment arrangements. However, every lender has its own eligibility criteria, underwriting process, documentation requirements, costs, and risk considerations. Businesses should carefully evaluate the lender and financing agreement before making a commitment.
What Are Private Business Lenders?
Private business lenders can include private lending companies, investment groups, specialized commercial finance firms, private investors, and other non-bank financial organizations that provide funding to businesses.
Unlike traditional banks, private lenders may use different approaches when assessing a business financing application. Depending on the lender, the assessment may consider factors such as business revenue, cash flow, assets, credit history, collateral, existing obligations, industry, business plan, and the intended use of funds.
Private financing may be structured for short-term or longer-term requirements. Some lenders specialize in specific industries or financing purposes, while others may focus on particular types of businesses, projects, or assets.
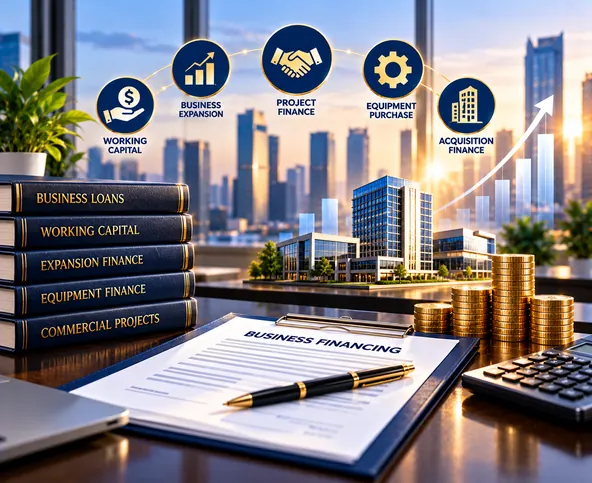
Companies may seek private business financing for a variety of commercial requirements. Common purposes include:
- Business Expansion: Opening new locations, entering new markets, or increasing operational capacity.
- Working Capital: Managing payroll, inventory, suppliers, operating expenses, or temporary cash-flow requirements.
- Equipment Financing: Purchasing machinery, technology, vehicles, or other business assets.
- Commercial Projects: Funding construction, development, or other project-related expenses.
- Business Acquisition: Supporting the purchase or expansion of an existing business.
- Bridge Financing: Providing temporary funding while a business waits for another source of capital.
- Refinancing: Restructuring or replacing certain existing commercial obligations where appropriate.
The suitability of private financing depends on the company’s circumstances and the terms offered by the lender.
How Does Private Business Lending Work?
The private business lending process can vary between lenders, but it generally involves several stages.
1. Initial Application
The business provides information about its financing requirement, desired loan amount, purpose of funds, business structure, and expected repayment ability.
2. Financial and Business Review
The lender may review financial statements, revenue, bank statements, tax records, credit history, assets, existing liabilities, and other business information.
3. Due Diligence
Depending on the transaction, the lender may conduct identity verification, business verification, credit checks, legal reviews, and other due-diligence procedures.
4. Financing Proposal
If the business meets the lender’s criteria, the lender may provide proposed financing terms. These can include the financing amount, interest or other financing costs, repayment schedule, fees, collateral requirements, and other conditions.
5. Documentation and Approval
The business reviews the proposed agreement and provides any additional documents required by the lender. Final approval remains subject to the lender’s assessment and conditions.
6. Funding and Repayment
Once the agreement is finalized, funds are provided according to the agreed terms. The borrower then follows the specified repayment schedule and other contractual obligations.
Private Business Lenders vs. Traditional Banks
Private lenders and traditional banks can both provide business financing, but their approaches may differ.
Banks often operate under established lending policies and may require detailed financial and credit assessments. Private lenders may offer different financing structures and may assess factors beyond traditional credit criteria.
However, businesses should not assume that private financing is automatically faster, easier, or less expensive than bank financing. The cost and conditions depend on the lender, borrower, transaction structure, collateral, financing period, and associated risks.
How to Choose a Private Business Lender
Businesses should conduct appropriate due diligence before selecting a private lender. Important considerations include:
Lender Reputation and Identity
Verify the lender’s legal business information, operating history, and relevant credentials.
Financing Terms
Review the total financing cost, interest rate or other charges, repayment schedule, fees, prepayment conditions, and default provisions.
Collateral Requirements
Understand whether business assets, property, receivables, personal guarantees, or other forms of security are required.
Funding Timeline
Ask the lender to explain the expected processing and funding timeline without relying on unsupported guarantees.
Contractual Obligations
Read the complete financing agreement carefully and ensure that all obligations and conditions are understood before signing.
Private Business Financing for Growing Companies
Private financing may be considered by businesses that have specific capital requirements but need to explore alternatives to conventional bank lending. For example, a company experiencing rapid growth may require additional working capital, while an established business may need funding for an acquisition or commercial project.
A financing decision should be based on the company’s ability to manage the associated obligations. Businesses should consider expected cash flow, repayment requirements, financing costs, collateral exposure, and the potential impact on future operations.
Important Considerations Before Borrowing
Private business financing should be approached with careful financial planning. Businesses should calculate the total cost of financing rather than focusing only on the amount they can borrow.
Applicants should also be cautious about claims involving guaranteed approval, guaranteed funding, zero-risk financing, or unusually favorable terms. All important terms should be provided in writing and independently reviewed where appropriate.
For significant financing arrangements, businesses may consider obtaining independent legal, accounting, or financial advice before signing an agreement.

FAQ’s
Frequently Asked Questions
Browse our most common questions about fees, identification, mobile services, and legal
requirements.
Private business lenders are non-bank financing providers such as private lending companies, investment groups, specialized finance firms, or private investors that provide funding to eligible businesses.
Depending on the lender and financing agreement, funding may be used for working capital, expansion, equipment, acquisitions, commercial projects, inventory, refinancing, or other legitimate business purposes.
Eligibility varies by lender. Factors may include business revenue, cash flow, credit history, assets, collateral, industry, operating history, financial statements, and the intended use of funds.
Yes. Private lenders and banks may use different financing structures, eligibility criteria, underwriting approaches, and pricing models. Businesses should compare the complete terms rather than assuming one option is automatically more suitable.
There is no universal amount. The available financing depends on the lender’s criteria, the company’s financial position, repayment capacity, collateral, project requirements, and the proposed financing structure.
Verify the lender’s identity and business information, then carefully review financing costs, repayment terms, fees, collateral requirements, default provisions, and other contractual obligations before proceeding.